• (941) 704-6255

Why Us2026-08-27T03:04:21+00:00

Protecting What Matters Most

Welcome to Dobson Health Insurance Group, a trusted health insurance agency established in 2008 and serving individuals, families, and businesses nationwide.

At Dobson Health Insurance Group, we understand that choosing health insurance can feel overwhelming. With so many plans, options, and coverage considerations, finding the right solution can be challenging. Our passion is helping people navigate their health insurance options and find coverage that fits their individual needs.

We offer a wide range of health insurance solutions, including individual and family health plans, group health insurance, and Medicare options. Our goal is simple: to help our clients understand their choices and find coverage that provides the protection they need.

  • Knowing the Proper Coverage

  • Finding the best products & best prices

  • Eliminating fluff that inflates the cost

” I make sure my clients know their options, their coverages & what to expect. “

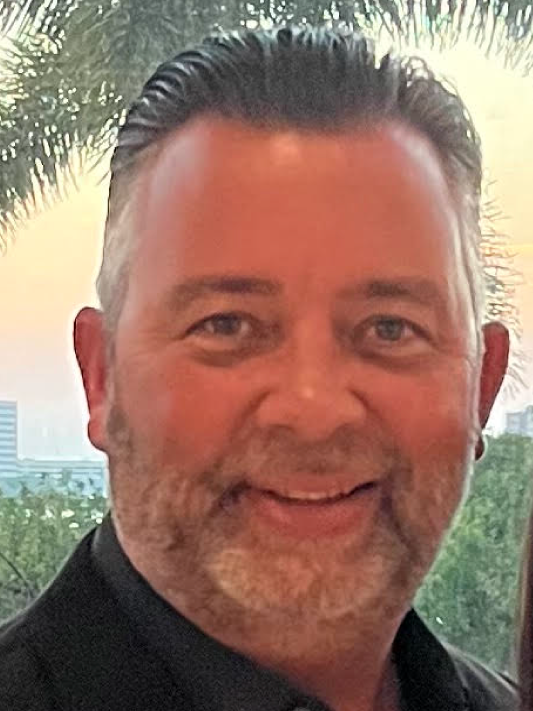
Chip Dobson

Founder & CEO
Dobson Health Insurance Agency
Built on Honor, Integrity & Commitment

Our core values are deeply rooted in service. As a proud United States Air Force veteran, I carry forward the principles that shaped my service: honor, integrity, and commitment to others.

These values guide the way we serve our clients every day. We believe in treating people with respect, listening to their needs, and working diligently to find solutions that are right for them.

At Dobson Health Insurance Group, we don’t believe in a one-size-fits-all approach. Every individual, family, and business has unique circumstances and health insurance needs. That’s why we take the time to understand your situation and help you explore your available options.

Our Commitment to You

Since 2008, our mission has been to preserve the integrity of our business while providing dependable, personalized service to the people we serve.

Whether you’re looking for individual or family coverage, exploring group health insurance for your business, or considering your Medicare options, we’re here to help you navigate the process with confidence.

Your health coverage matters. Let us help you explore your options.
Let’s Work Together to Create Your Health Insurance Plan

“Chip helped me settle on a health insurance plan that had all of the coverage I needed, it kept my current doctor and allowed me to continue seeing a specialist in my network & covered my prescriptions. He did it all within my budget.”

Andre C.

Current Dobson Health Client
Chip Dobson

Health Insurance Expert

Get Covered. Explore Your Options. Move Forward With Confidence.

What problem are you trying to solve?

Does my small business have to offer health insurance?2026-08-27T13:19:45+00:00

Only if you have 50 or more full-time equivalent employees. Below that, there is no federal requirement at all, and the IRS notes that “the vast majority of employers will fall below the ALE threshold.”

A full-time employee is anyone averaging 30 hours a week or 130 hours a month. Part-time hours get combined into full-time equivalents, so add those up before assuming you are under. At 50 or more, you either offer affordable coverage that meets minimum value or you potentially owe a payment. For 2027 those amounts are $3,780 per full-time employee if you offer nothing, or $5,670 per employee who gets a marketplace subsidy if your coverage is unaffordable.

Two things worth knowing if you are under 50 and want to offer coverage anyway. You may qualify for the Small Business Health Care Tax Credit, worth up to 50% of your premium contributions, if you have fewer than 25 full-time equivalent employees, pay average annual wages under about $69,000, cover at least half of each employee’s premium, and buy through SHOP. And if you cannot hit a carrier’s minimum participation requirement, federal rules require carriers to sell to you anyway during a November 15 through December 15 window each year.

Is it illegal to not have health insurance?2026-08-27T13:19:34+00:00

No. It is not illegal, and there has been no federal penalty since 2019. The Tax Cuts and Jobs Act reduced the individual mandate payment to zero for months beginning after December 31, 2018.

Five places still impose a state penalty: Massachusetts, New Jersey, California, Rhode Island, and Washington DC. Vermont requires you to report coverage on your return but charges nothing if you do not have it. Maryland has no penalty either. It just puts a checkbox on your tax return that can start an application.

Being uninsured is legal. It is also the reason medical debt is the leading cause of personal bankruptcy in this country. And if you skip coverage now, you generally cannot buy it mid-year when something happens. You would be waiting for the next open enrollment.

What is the difference between an HMO, PPO, EPO, and POS plan?2026-08-27T13:19:24+00:00

The difference comes down to two things: whether you need a referral, and whether out-of-network care is covered at all.

  • HMO keeps care inside its network and generally will not cover out-of-network care except in an emergency. Usually requires a primary care doctor and referrals. Typically the lowest premium.
  • PPO contracts with a network but lets you go outside it at a higher cost. No referral needed. Typically the highest premium.
  • EPO covers only in-network providers, like an HMO, but usually skips the referral requirement.
  • POS costs less in-network and does require a referral from your primary care doctor to see a specialist.

Before you choose, check the actual provider directory for your doctors and the drug formulary for your prescriptions. Network is where plans quietly differ most, and it is not visible in the premium.

What is the difference between a premium, deductible, copay, coinsurance, and out-of-pocket maximum?2026-08-27T13:19:13+00:00

These are the five numbers that decide what a plan really costs you.

  • Premium is what you pay every month to keep the plan, whether you use it or not.
  • Deductible is what you pay for covered care before the plan starts paying. With a $2,000 deductible, you cover the first $2,000.
  • Copay is a flat amount for a specific service, like $30 for an office visit.
  • Coinsurance is a percentage of the bill after your deductible is met. At 20% coinsurance on a $100 service, you pay $20.
  • Out-of-pocket maximum is your ceiling. Once you hit it, the plan pays 100% of covered in-network care for the rest of the year.

For 2027, federal law caps out-of-pocket costs at $12,000 for an individual and $24,000 for a family. Monthly premiums, out-of-network care, and anything the plan does not cover do not count toward that ceiling.

Do I still qualify for a subsidy?2026-08-27T13:18:58+00:00

Possibly, but the rules tightened. The enhanced premium tax credits that ran from 2021 through 2025 expired on December 31, 2025 and have not been extended.

Two things changed. The 400% federal poverty level cap came back, so there is a hard income cliff again. For 2027 coverage that is roughly $63,840 for one person and $132,000 for a family of four. One dollar over and the credit disappears entirely. And the share of income you are expected to pay went up, from a 0% to 8.5% range under the old rules to 2.15% to 10.22% for 2027.

There is a second change almost nobody is talking about. Starting with the 2026 tax year, the cap on repaying excess advance credits is gone. If you underestimate your income, you repay all of it at tax time, with no dollar ceiling. Tell your broker right away if your income changes mid-year.

Bills to restore the enhanced credits are still pending in Congress. Nothing has passed.

How much does health insurance cost per month?2026-08-27T13:18:43+00:00

It depends on your age, ZIP code, household size, tobacco use, the plan you pick, and your income. Here is what people actually paid in 2026.

On the ACA marketplace, the average benchmark plan ran $625 a month for a 40-year-old before any assistance. After premium tax credits, the average enrollee paid $178 a month, up from $113 the year before.

Through an employer, the average total cost in 2025 was $9,325 a year for single coverage and $26,993 for a family. Workers paid $1,440 and $6,850 of that respectively. The employer covered the rest.

Sticker price is a poor guide here. A plan with a low premium and a $9,000 deductible can cost you far more than a pricier plan if you actually use it. That comparison is the whole job.

Can I get health insurance outside of open enrollment?2026-08-27T13:18:22+00:00

Yes, if you have a qualifying life event. That opens a Special Enrollment Period, and you generally have 60 days from the event to pick a plan.

Events that qualify include losing job-based, Medicaid, CHIP, or student coverage, turning 26 and aging off a parent’s plan, getting married, having or adopting a child, divorce or separation that costs you coverage, moving to a new ZIP or county, gaining citizenship, leaving incarceration, and being offered an ICHRA or QSEHRA by an employer.

Two details people get wrong. If you are losing coverage, you can enroll up to 60 days before it ends, which avoids a gap entirely. And losing Medicaid or CHIP gives you 90 days, not 60.

What does not qualify: voluntarily dropping your coverage, or losing it because you stopped paying the premium. If you claim a loss-of-coverage event, expect to submit documentation within 30 days of picking a plan.

When is open enrollment for health insurance?2026-08-27T13:18:11+00:00

For 2027 coverage on HealthCare.gov, open enrollment runs November 1, 2026 through January 15, 2027. CMS confirmed those dates in a July 27, 2026 statement.

Two deadlines matter inside that window:

  • Enroll by December 15 and your coverage starts January 1.
  • Enroll December 16 through January 15 and coverage starts February 1.

A shortened window ending December 15 was finalized in a 2025 rule, but a federal court vacated that provision in June 2026. The full window is what is in effect. Some state-run exchanges set their own dates. Covered California runs through January 31. Idaho is the outlier and runs October 15 through December 15.

Employer plans and Medicaid follow different calendars. Medicaid and CHIP have no open enrollment at all. You can apply any time of year.

How do I know a health insurance broker is legitimate?2026-08-27T13:17:58+00:00

Check two things, and both take about a minute.

First, confirm an active health line of authority with your state’s department of insurance. Every state runs a free license lookup. Second, if the broker is helping you with a Marketplace plan, confirm he appears on the CMS Agent and Broker Registration Completion List for the current plan year. Marketplace registration and training have to be renewed every single year.

Also know your rights. A broker must have your permission before enrolling you or changing your plan. In July 2024, CMS blocked agents from altering a consumer’s enrollment unless they were already associated with it, specifically to stop unauthorized plan switching. If something looks wrong with your coverage, call the Marketplace at 1-800-318-2596. They can cancel an unauthorized plan, get incorrect charges repaid, and issue corrected tax forms.

What is the difference between an agent, a broker, and a Marketplace navigator?2026-08-27T13:17:44+00:00

HealthCare.gov puts it simply: “Agents may work for a single health insurance company; brokers may represent several companies.”

A navigator or certified application counselor is trained and certified by the Marketplace, works for free, and is “required to be unbiased.” That last part matters more than it sounds. Navigators can walk you through the application, but they are not permitted to recommend a specific plan. A licensed broker can look at your doctors, your prescriptions, and your budget and tell you which plan he would put his own family on.

Both can help you apply. Only one can give you a recommendation.

How does a health insurance broker get paid?2026-08-27T13:17:30+00:00

The insurance company pays the broker a commission when you enroll, and again each month or year you keep the plan. You are never billed for it.

Commissions sit inside the administrative cost portion of the rate an insurer files with regulators. Federal rules at 45 CFR 156.80(d)(2) list every factor that is allowed to change a plan’s price, and sales channel is not one of them. That is why the price is identical everywhere.

One fair question to ask any broker: which carriers are you appointed with? An independent broker who represents several companies can compare across them. A captive agent can only sell one.

Does it cost more to buy health insurance through a broker?2026-08-27T13:17:18+00:00

No. You pay the same premium whether you buy through a broker, directly from the insurance company, or on HealthCare.gov. That is not a courtesy, it is federal law. Under 45 CFR 156.255(b), an insurer “must charge the same premium rate without regard to whether the plan is offered through an Exchange, or whether the plan is offered directly from the issuer or through an agent.”

The broker’s commission is already built into the rate the insurer filed with your state. It is there whether you use a broker or not. Going direct does not remove it from your premium. It just means nobody is helping you.